

FatTail Week Ahead · Sunday, November 1, 2026 · all times ET
Volatility abstract
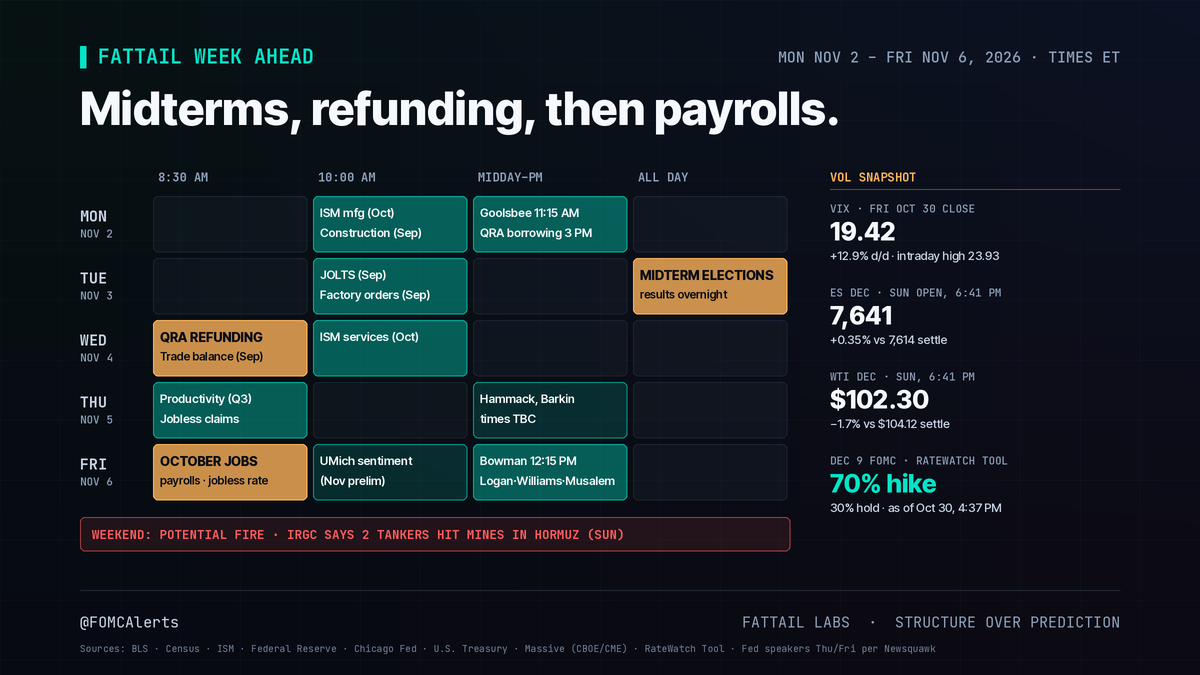
Vol came into the weekend bid. The VIX closed Friday, Oct 30 at 19.42, up from 17.20 Thursday (+12.9%), after trading as high as 23.93 during the session. The S&P 500 closed at 7,580.07, down 1.8% on the day. The 10-year Treasury yield was 4.98% on Oct 29, the latest reading we have; Friday’s close was unavailable to us at publication.
The Sunday 6 PM reopen was calmer than the weekend headlines. At about 6:41 PM ET, December S&P 500 e-mini futures traded at 7,641, up 27 points (+0.35%) from Friday’s 7,614 settle. December WTI crude was $102.30, down 1.7% from its $104.12 settle. A VIX futures quote was unavailable to us at publication.
Fed pricing is the backdrop. The RateWatch Tool showed a 70.4% chance of a 25 bp hike at the Dec 9 FOMC meeting and 29.6% for a hold, as of Friday, Oct 30 at 4:37 PM ET. That hike probability was 16.6 points lower than on Oct 28. The target range is 3.75%–4.00%. This week’s data can move that number. Payrolls on Friday matter most, and a Fed with that much hike risk priced in leaves little room for a surprise to go unpriced.
Weekend geo-macro check: potential fire
The Strait of Hormuz is the story again. On Sunday afternoon, Iran’s IRGC navy said two tankers exploded on mines while using what it called an unauthorized route, and that one was a burning supertanker. Reuters, Middle East Eye and Iran International carried the claim, as did The Jerusalem Post, which also cited UKMTO reporting a separate tanker hit by a projectile. These follow Iran’s late-week claims of tankers striking mines in the strait.
Diplomacy is running at the same time. US–Iran indirect talks in Doha went into a third day, and The Guardian reported that negotiators were braced for the worst. Elsewhere the weekend leaned calmer: OPEC+ kept December output targets steady, Canada’s Carney described a “good conversation” with Trump on trade, and oil futures had eased Sunday morning on hopes for diplomacy.
Verdict: potential fire. A new mine incident in the world’s key oil chokepoint, while talks are underway, could reprice oil and vol quickly. So far the reopen has not done that (ES up, WTI down), so we treat this as a live risk to watch, not a move that has already happened.
The calendar, Monday to Friday
Times are ET. Dates come from the issuing agency unless we note otherwise.
Monday, Nov 2
- 10:00 AM: ISM Manufacturing PMI (Oct) (ISM) and Construction Spending (Sep) (Census). ISM’s prices-paid index is the first read on whether the oil shock is moving into factory costs, and that is the hawkish channel for December.
- 11:15 AM: Chicago Fed President Goolsbee moderates a Q&A with the BIS’s Andréa Maechler at the Chicago Fed’s Financial Markets Group conference (Chicago Fed).
- 2:00 PM: Senior Loan Officer Survey (SLOOS) (Federal Reserve). It shows how much credit conditions have tightened ahead of a possible hike.
- 3:00 PM: Treasury marketable borrowing estimates (Treasury). This is the first half of the quarterly refunding and sets the borrowing math for Wednesday.
Tuesday, Nov 3
- U.S. midterm elections. Results arrive overnight into Wednesday, so overnight gap risk in index futures is higher than usual.
- 10:00 AM: JOLTS (Sep) (BLS) and factory orders, full report (Sep) (Census). Openings and quits are the labor-demand check ahead of Friday.
Wednesday, Nov 4
- 8:30 AM: Treasury quarterly refunding statement, with the TBAC report and minutes (Treasury). Bloomberg flagged a possible overhaul of auction sizes, one of the largest in years. With the 10-year near 5%, any shift toward longer maturities would hit term premium and, through it, equity vol.
- 8:30 AM: International trade in goods and services (Sep) (Census/BEA).
- 8:15 AM: ADP employment (Oct). This is ADP’s usual Wednesday slot; we did not confirm the date and time on ADP’s own calendar.
- 10:00 AM: ISM Services PMI (Oct) (ISM). Services prices paid are the inflation input the Fed watches most closely.
Thursday, Nov 5
- 8:30 AM: Productivity and Costs, preliminary (Q3) (BLS). Unit labor costs are the wage-inflation signal in this report.
- 8:30 AM: initial jobless claims (Labor Department’s usual weekly Thursday release).
- Fed speakers: Cleveland’s Hammack and Richmond’s Barkin. This listing comes from Newsquawk’s weekly calendar; times are not yet confirmed by the reserve banks.
- 4:30 PM: Fed balance sheet (H.4.1) (Federal Reserve).
Friday, Nov 6
- 8:30 AM: Employment Situation (Oct) (BLS). This is the week’s biggest event for Fed odds. Previews we’ve seen put consensus payrolls at +55K (CNBC) to +65K (Seeking Alpha), with unemployment at 4.2% (CNBC); September was +29K (Seeking Alpha). A firm wage number keeps a December hike priced in. A weak report would test the 70% hike odds.
- 10:00 AM: University of Michigan sentiment, preliminary (Nov). This is the usual slot; we have not checked it against UMich’s calendar. Watch inflation expectations with oil above $100.
- 12:15 PM: Fed Vice Chair for Supervision Bowman discusses supervision and regulation at the University of Mississippi (Federal Reserve).
- Fed speakers: Dallas’s Logan, New York’s Williams and St. Louis’s Musalem (from Newsquawk’s calendar; times not confirmed). Logan said on Oct 30 that she sees a need for at least two more hikes.
- 3:00 PM: Consumer credit (G.19) (Federal Reserve).
Also this week: central bank decisions from the RBA (Tue), Riksbank and Brazil’s BCB (Wed), and the Bank of England, Norges Bank and Banxico (Thu); Canada’s federal budget (Thu); and Apple (Mon) and AMD (Tue) earnings. The Fed’s Oct 27–28 minutes are out Nov 18, and the next FOMC decision is Dec 9. Follow live coverage on the FOMC Alerts Hub.
What it means for 0DTE
- Energy: The scheduled risk is concentrated in three windows: Tuesday night (election), Wednesday 8:30–10:00 AM (refunding, trade, ISM Services) and Friday 8:30 AM (payrolls). Hormuz is the unscheduled risk that can hit at any hour.
- Premium: Friday’s VIX close of 19.42 and 23.93 intraday high mean premium is no longer cheap. Expect implied vol to build into Friday’s jobs report and crush after it.
- Structure: Use defined risk and know the maximum loss before entry. With an election night and a jobs report this week, size for gaps.
- Plan, don’t predict: Map out both cases ahead of time: a hot jobs report with December hike odds rising back toward the Oct 28 level, and a soft report with odds falling. Don’t bet on a direction in advance.
Sources
- Release schedule, November 2026 (Bureau of Labor Statistics, 2026)
- Economic Indicator Calendar 2026 (U.S. Census Bureau, 2026)
- Report Release Date Calendar (ISM, 2026)
- Calendar (Federal Reserve Board, Nov 2026)
- Financial Markets Group Fall Conference (Federal Reserve Bank of Chicago, Nov 2, 2026)
- Most Recent Quarterly Refunding Documents (U.S. Treasury, Nov 2026)
- Newsquawk Weekly Economic Calendar, 2nd–6th November 2026 (Newsquawk, Oct 30, 2026)
- Two oil tankers explode after hitting mine in Hormuz Strait, IRGC spokesperson says (The Jerusalem Post, Nov 1, 2026)
- Negotiators 'braced for worst' over US-Iran talks to reopen strait of Hormuz (The Guardian, Nov 1, 2026)
Trade it with structure
Observer is a six-week trial and training program: train with Coach for $17/week. You get everything a full coaching member gets, every week, and the six weeks are designed to install pro trading habits: courses on strategy, process and risk management, live daily coaching, a Discord trade room with hundreds of experienced traders, and the platform (heatmap, GEX tools, risk graph, position analyzer and journal). Start Observer.
Educational content, not investment advice. Options involve risk and are not suitable for all investors.
FATTAIL BRIEFINGS
Get FatTail briefings in your inbox
Pick the lists you want. FOMC Alerts is selected by default.