

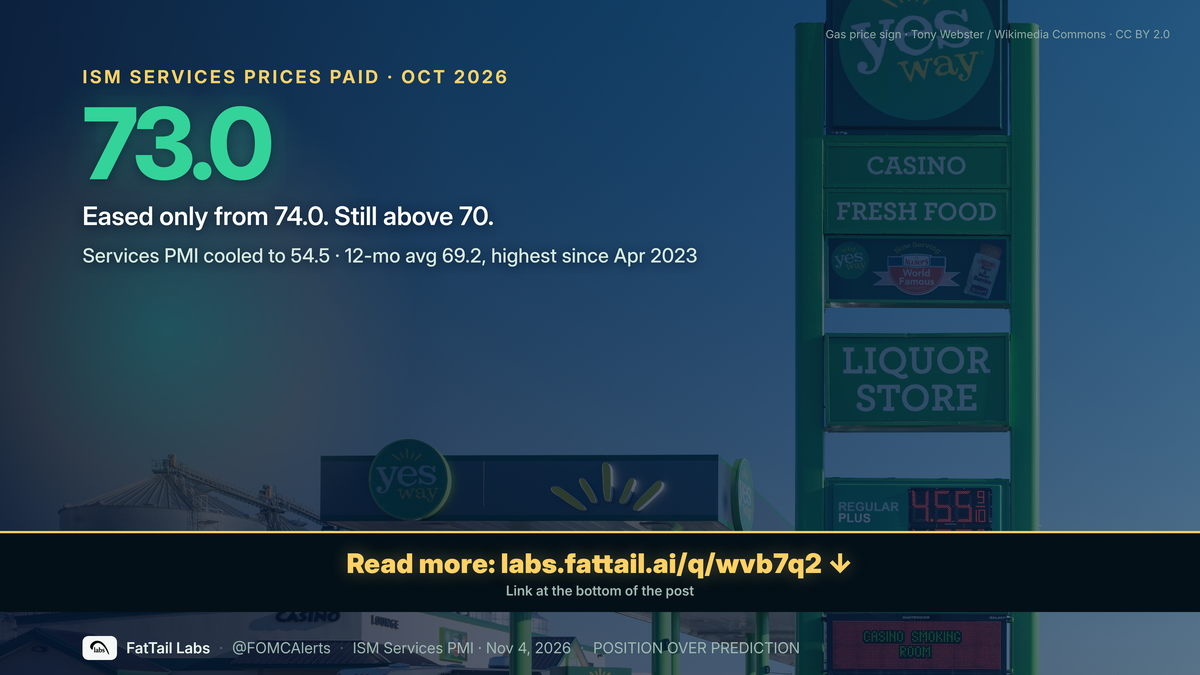
Services cooled in October. Prices didn’t cool much. The ISM services PMI for October 2026 slipped to 54.5 from 54.9 in September, a little under the 54.8 consensus (third-party estimate). But the Prices Index eased only to 73.0 from 74.0, one point off a very high level. It is still well above 70.
ISM services PMI October 2026: the numbers
ISM released the report at 10:00 AM ET on Nov 4. Every one of its 10 indexes was in expansion territory, the first time that has happened since February 2026.
| Index | October | September |
|---|---|---|
| Services PMI | 54.5 | 54.9 |
| Business Activity | 53.8 | 56.5 |
| New Orders | 55.9 | 59.8 |
| Employment | 51.4 | 50.1 |
| Supplier Deliveries | 56.7 | 53.2 |
| Prices | 73.0 | 74.0 |
| Backlog of Orders | 58.0 | 56.6 |
| Inventories | 55.4 | 57.8 |
| New Export Orders | 55.2 | 46.9 |
| Imports | 54.2 | 52.9 |
Source: ISM, October 2026 Services PMI Report.
Activity and new orders both lost ground but are still growing. The Backlog of Orders Index climbed to 58.0, its highest reading since July 2022. Fifteen industries grew, while Construction and Health Care contracted.
Prices paid: eased, but only to 73
The Prices Index fell 1 point to 73.0. That is the seventh reading above 70 in eight months, and it sits 3.8 points above the index’s 12-month average of 69.2, which is itself the highest since April 2023. Services firms have reported paying more for 113 straight months. No commodities were reported down in price.
ISM’s Steve Miller said “many respondents indicated they are not yet seeing the full impact of these cost escalations or have not passed them through to customers.” ISM read that as a sign that more pricing pressure is on the way if oil and tariff costs are not mitigated.
One respondent in the Information industry put it plainly: “Fuel prices are impacting many of our consumables and delivered goods. This has reduced margins, as we have not passed the expense to our customers because we believe it will be a short-term condition.”
Manufacturing showed the same pattern earlier this week. Its prices index eased to 75.2 from 77.9. Both surveys are easing from very high levels, and both are still above 70.
Advertisement · From FatTail Labs

Observer: train with Coach for $17/week
A six-week trial and training program built to install pro trading habits: live daily coaching, courses, a Discord trade room and the full FatTail platform.
Jobs read-through
Services employment rose to 51.4, its second month in a row above 50. Friday’s payrolls report is the next test. The consensus is +65K after September’s +29K, with unemployment at 4.2% (Reuters poll, third-party).
Tutorial: how to read the ISM Services report
- Services PMI. A monthly survey of purchasing managers at services firms. A reading above 50 means the sector is expanding. The headline averages four parts: business activity, new orders, employment and supplier deliveries.
- Prices Index. This is a diffusion index. It measures how many firms report paying more, not how much more they pay. A reading of 73 means price increases are widespread. It does not mean prices rose 73%, and it says nothing about how big the increases were.
- Why 0DTE SPX and VIX traders care. A hot prices index can shift rate expectations and front-end yields, and that can reprice SPX intraday along with the cost of short-dated options. For how to map a print like this into scenarios before the open, see our 0DTE SPX scenario planning guide.
The Fed and the market
The Fed, chaired by Warsh, holds rates at 3.75–4.00%. For the Dec 9 meeting, RateWatch shows a 68.6% chance of a 25bp hike and 31.4% for a hold, as of 4:41 PM ET Thu Nov 5. That is a level, not a reaction to this report. For how those odds have moved, see December Fed rate hike odds and the live RateWatch tool.
Market levels: SPX 7,688.56 (+1.58%) and VIX 16.73 at about 4:03 PM ET Wed Nov 4 (Massive). These are levels only. Wednesday’s session also carried the midterm results, so none of the move is attributed to ISM.
ISM comes out at 10:00 AM ET. For 0DTE traders, the prices index matters less as a same-day mover than as an input to the CPI report on Nov 10 and to the Dec 9 debate (see the FOMC meeting schedule 2026). More Fed coverage: FOMC Alerts.
Source
- Services PMI at 54.5%; October 2026 ISM Services PMI Report (Institute for Supply Management (via PR Newswire), 2026-11-04)
Bottom line
Demand cooled a little, backlogs built and every index expanded. The price signal eased by just one point, to 73.0, and ISM’s respondents say more cost pass-through may still be ahead. This is one input to Dec 9, not a call. Position over prediction.
FATTAIL BRIEFINGS
Get FatTail briefings in your inbox
Pick the lists you want. FOMC Alerts is selected by default.