

Warsh on AI and inflation, in official words
A Washington Post lede this morning, by Steve Thompson, framed Chair Kevin Warsh as an outlier who doubts that AI is driving up inflation, against colleagues who say the boom is fueling it. The captured text is the headline, dek, and lede only; the paper is paywalled, and we do not have a full reprint. Warsh has chaired the FOMC since May 22, 2026. This warsh ai inflation piece puts official words on the table. It does not adopt an unverified headcount of colleagues, and it does not treat “tame inflation” as a sentence he said.
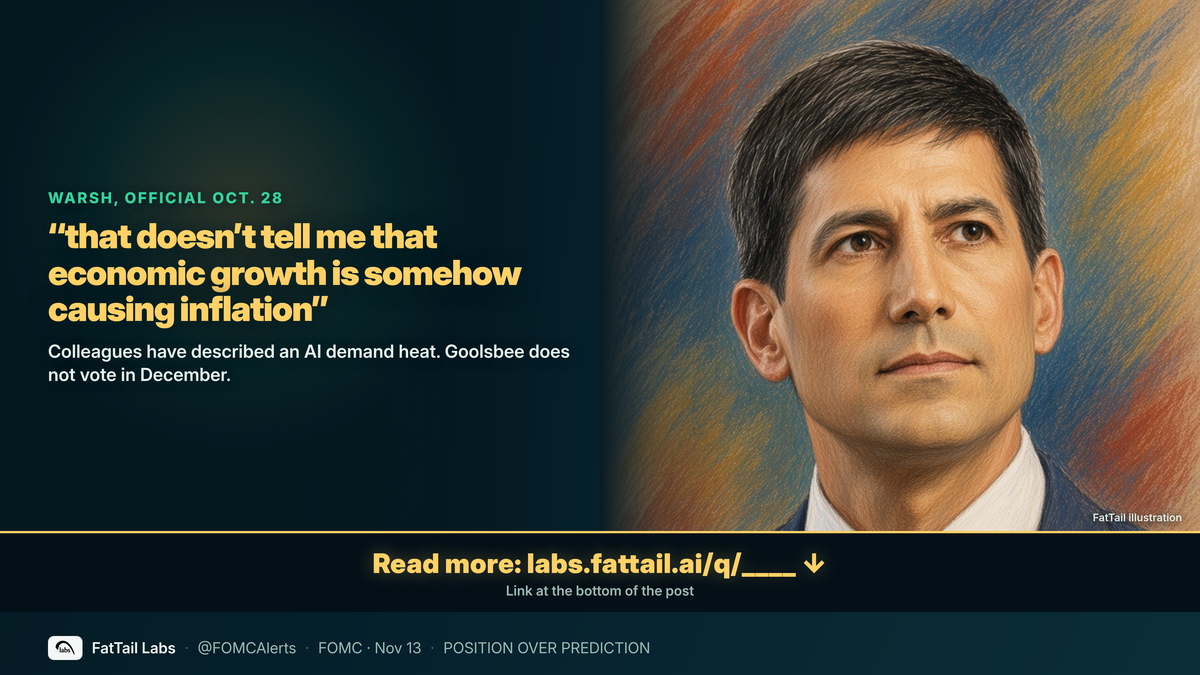
At the Oct. 28 press conference, Warsh said: “And so economic growth is higher, but that doesn’t tell me that economic growth is somehow causing inflation and making our job harder.” That is not a denial that AI is raising any prices. In official remarks this year he has said the demand side of the AI buildout is showing up in GDP, and that the capex boom is driving up prices of memory and logic chips and associated AI infrastructure — then asked whether that is a broader inflationary dynamic or a narrower, relative-price effect. At Jackson Hole he posed open questions about whether AI would cause a significant, sustained rise in productivity, and when, and said the Productivity and Jobs Task Force would not bind the current policy conjuncture.
What colleagues have said — and who votes in December
Chicago Fed President Austan Goolsbee, a 2026 FOMC alternate who does not vote at the Dec. 8–9 meeting and is a 2027 voter, put a demand-heat reading on the same buildout today. In a CNBC Squawk Box interview, caption-verified, he said: “A lot of times the conventional wisdom says, look through supply shocks because they can go away quickly. Nobody says that if demand is overheating. And what we’ve seen over the last six months, let’s say, is this data center build out coming from AI, has been heating up the economy.”
That is a real disagreement about the inflation channel — narrow or relative-price pressure versus broader demand overheating — not a vote count and not a forecast of December. Goolsbee’s remarks are his own; he is not a 2026 voter. This piece does not recast other recent AI comments from Governors Barr or Bowman, which were about labor-market disruptions and equity-correction risk, as CPI-inflation testimony. Voting roster: 2026 FOMC voters. Earlier Goolsbee context: Goolsbee on inflation. Adjacent labor-market reading: Barr on the labor share and AI.
The official Productivity and Jobs Task Force conference is Monday, Nov. 16, at the San Francisco Fed, with Warsh’s opening remarks scheduled for 9:00–9:15 a.m. PT (12:00–12:15 p.m. ET), livestreamed. This article is not being held for those remarks; they are a follow-up if he speaks again to prices. Event page: SF Fed conference listing.
Advertisement · From FatTail Labs

Observer: train with Coach for $17/week
A six-week trial and training program built to install pro trading habits: live daily coaching, courses, a Discord trade room and the full FatTail platform.
Policy context and what it means for 0DTE
The current federal funds target range is 3¾ to 4 percent, after a 25 bp hike on Sept. 16 (12–0) and a hold on Oct. 28 (10–2). The next scheduled decision is Dec. 8–9. RateWatch, FatTail’s house ZQ-method reading, shows, as of 2026-11-13 13:46:44 EST, a December hike at 100% and a hold at 0%; of that hike, +25 bp is 89.4% and +50 bp is 10.6%. January is 68.9% hike / 31.1% hold, and March is 65.0% hike / 35.0% hold. Those are single current levels with an as-of stamp, not a reaction to the WaPo lede, to Warsh, or to any other event. Live odds: RateWatch. Meeting calendar: December FOMC 2026 · October 28 FOMC decision.
On the tape, this is a same-day policy-color piece, not a scheduled print and not a decision. We are not treating Friday’s in-session tape as an official close, and we are not attributing any midday move to the article or the lede. Last official cash close, Thursday Nov. 12: S&P 500 7,592.40, VIX 18.70, VIX1D 15.99.
- Energy: Official-text color on the AI-and-inflation channel, useful for the December book, not a typical vol event and not a vote.
- Premium: Let implied vol price the session; do not treat a newspaper lede or a press-conference line as if it were the Dec. 9 statement.
- Structure: Defined risk only, with max loss known before entry, especially with October PCE still ahead on Nov. 25 and the FOMC just over three weeks out.
- Plan, don’t predict: The fact is Warsh’s official view that higher growth, by itself, does not tell him inflation is being caused and the job made harder, set against verified colleague language about demand heat from the AI buildout. Whether that maps to a December increment stays with the committee, not in a directional bet.
Related reading: Goolsbee on inflation · Barr on AI and the labor share · RateWatch · December FOMC 2026
Sources
- FOMC press conference transcript (FINAL PDF), Oct. 28, 2026 (Board of Governors of the Federal Reserve System, 2026-10-28)
- CNBC Squawk Box interview with Austan Goolsbee (CNBC, caption-verified, 2026-11-13)
- The Fed chief said AI would tame inflation. His colleagues disagree. (lede only; paywalled) (The Washington Post, Steve Thompson, 2026-11-13)
- Productivity and Jobs Task Force conference (Federal Reserve Bank of San Francisco, 2026-11-16)
- Federal Reserve issues FOMC statement (Oct. 28, 2026) (Board of Governors of the Federal Reserve System, 2026-10-28)
- RateWatch odds_current.json (public file) (FatTail RateWatch, 2026-11-13)
FATTAIL BRIEFINGS
Get FatTail briefings in your inbox
Pick the lists you want. FOMC Alerts is selected by default.