

Bessent Goolsbee energy shock: two readings of inflation
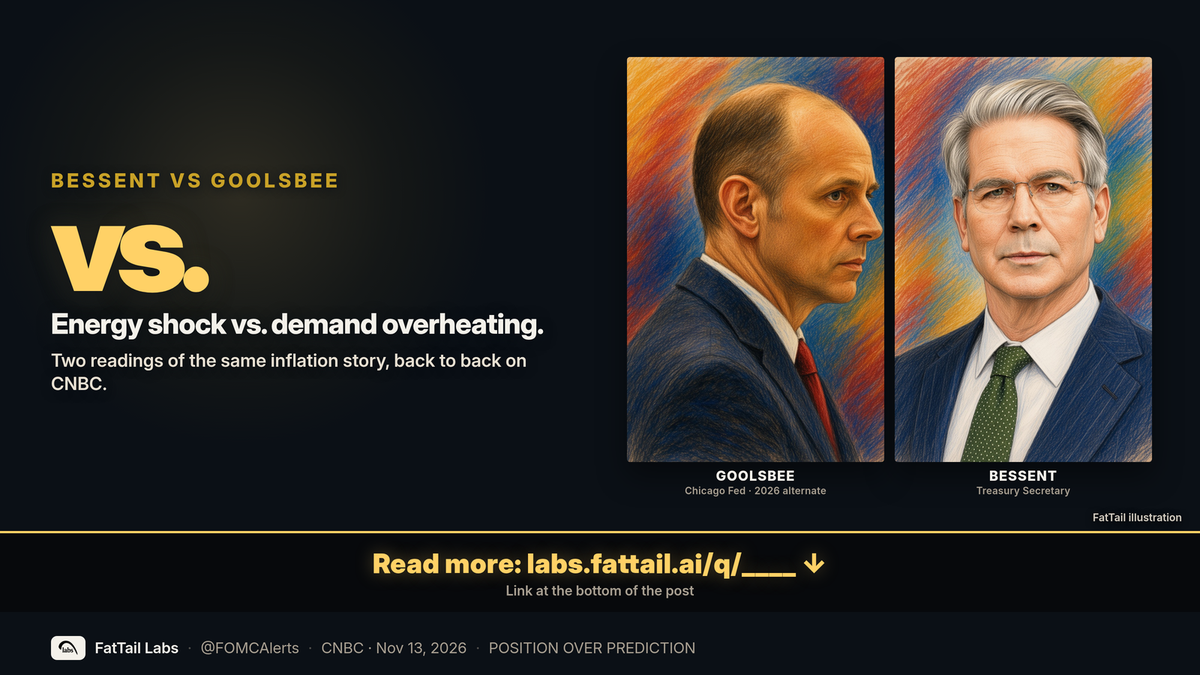
The Bessent Goolsbee energy shock split showed up in back-to-back CNBC Squawk Box interviews Friday morning. Treasury Secretary Scott Bessent, in official captions from the network’s video, said the inflation story is an energy supply shock and that hiking too much into it, when it is coming down, would be a mistake. Chicago Fed President Austan Goolsbee, on the same program after Bessent, described “old-fashioned demand overheating coming from the AI data center build-out that looks like it’s starting to spread out of its lane.”
Those are two readings of the same inflation print, not a vote call. Goolsbee is a 2026 FOMC alternate. He does not vote at the Dec. 8–9 meeting; he votes in 2027. Reuters later recast Bessent as saying the Fed should not hike because of an energy supply shock. That is the outlet’s paraphrase, not his wording, and it is not a claim that he ruled out a December hike.
What Bessent said — and what he didn’t
The official CNBC captions, not a Treasury transcript, are the wording used here. Bessent said, “I think the Fed should understand that this is an energy supply shock.” He added, “I think that to hike too much into an energy supply shock when it’s coming down. These are very noisy numbers.” And: “The Fed is supposed to look into the future, not look in the rear view mirror.”
On independence, he kept himself off the Committee: “I’m not going to tell the Fed what to do. I am going to say they should have an open mind.” Later: “And now to reverse just based on an energy supply shock, you know, a reversal in a dramatic way isn’t something that I would do if I were on the Fed, but I’m not on the Fed.” That refusal to dictate a path is the independence note, not a new crisis claim. For the earlier thread, see Trump vs. Warsh on Fed independence.
Bessent also cited his own market claims — that oil is down $20 this month, that gasoline is back below $4, and that diesel is down 10%. Those are his figures, not EIA or BLS prints. The official EIA weekly WTI series, for the week ending Nov. 6, is $95.97 a barrel, down from a recent weekly peak of $107.17 for the week ending Oct. 23. Official October CPI energy rose 0.7% on the month, and gasoline (all types) rose 1.0%; the not-seasonally-adjusted 12-month gasoline rate was 37.4%. There is still no official all-items or core CPI 12-month rate for October. For the CPI print itself, see October CPI 2026. This morning’s official PPI, a separate release, is October PPI 2026.
Advertisement · From FatTail Labs

Observer: train with Coach for $17/week
A six-week trial and training program built to install pro trading habits: live daily coaching, courses, a Discord trade room and the full FatTail platform.
Goolsbee’s demand-overheating case
Goolsbee’s caption wording is also the only wording used here. The hook is the build-out line above. On the 2% goal, he asked, “Are we on path back to 2%?” and answered, “My feeling is right now we’re not.” On credibility, the captions read: “I believe that the the central bank has definitely got work to do to continue to reestablish its credibility.” He again declined to choose between 25 and 50 basis points. Do not treat that refusal as a December vote. He is not a December 2026 voter; the 2026 roster is on the FOMC voters 2026 page.
Brooks’s case against hiking into a supply shock
Robin J. Brooks, a senior fellow in Economic Studies at the Brookings Institution and a former IIF chief economist, made the analytical case the same day in a Substack essay. Two lines, verbatim: “Another 50 or 100 basis points in hikes will do almost nothing to bring down inflation.” And: “That said, a 25 basis point hike in December is all but inevitable, but – because of all the ambiguity I discuss here – a 50 basis point hike won’t and shouldn’t happen.” He also wrote that the analytical case for three 25 basis point hikes through the end of next year, “which is what markets price, is weak.” That is his characterization of the tape, not a RateWatch label and not a forecast in this article.
RateWatch, as of 4:07 PM ET
As of 4:07 PM ET on Nov. 13, 2026, RateWatch — our ZQ futures method, never CME FedWatch — prices the Dec. 9 meeting as a 100% hike and a 0% hold, with +25 bp at 93.9% and +50 bp at 6.1%. The same stamp prices the Jan. 27 meeting at 71.2% hike / 28.8% hold, and the March 17 meeting at 66.7% hike / 33.3% hold. The current target range is 3.75–4.00%. That is a single snapshot, not a path of three certain hikes, and not a claim that this morning’s interviews or this morning’s PPI print moved those odds. RateWatch still prints rows for late 2027 dates that are not official 2027 policy meetings; do not treat those rows as decision odds.
What it means for 0DTE
Energy: The split is over the source of the inflation print — an energy supply shock versus demand overheating — with a 50 bp December hike still a minority outcome on the 4:07 PM ET RateWatch stamp. Keep the official caption wording, and Bessent’s own oil claims, separate from official EIA and CPI figures.
Premium: Thursday’s official close, Nov. 12, was S&P 500 7,592.40, VIX 18.70, and VIX1D 15.99, from Massive’s daily aggregates. Use that settled close as the last official reference until Friday’s official close is in. Do not treat an unofficial Friday print as the close, and do not attribute Friday’s tape to these interviews.
Structure: Defined-risk structures only. A same-day speaker split is not a reason to size up into a 25-versus-50 guess.
Plan: Keep the two official caption readings, the two Brooks lines, and the single RateWatch stamp as of 4:07 PM ET Nov. 13 on the pad. For a walkthrough of how we map a session onto a defined-risk plan, see how to plan 0DTE market scenarios.
Sources
- Watch CNBC's full interview with Treasury Sec. Scott Bessent (CNBC Squawk Box, 2026-11-13)
- The Case Against Fed Rate Hikes (Robin J. Brooks, Substack, 2026-11-13)
- Robin Brooks (Brookings Institution, 2026-11-13)
- RateWatch current odds (public JSON) (FatTail RateWatch, 2026-11-13)
- October CPI 2026 (FatTail, 2026-11-13)
Related reading
- Goolsbee on inflation
- October CPI 2026
- October PPI 2026
- RateWatch
- December Fed meeting 2026
- FOMC meeting schedule 2026
- FOMC voters 2026
- Trump vs. Warsh on Fed independence
- FOMC Alerts hub
FATTAIL BRIEFINGS
Get FatTail briefings in your inbox
Pick the lists you want. FOMC Alerts is selected by default.