


FatTail Retrospective · Week of Monday, November 9 to Friday, November 13, 2026 · all times ET
The week in one line
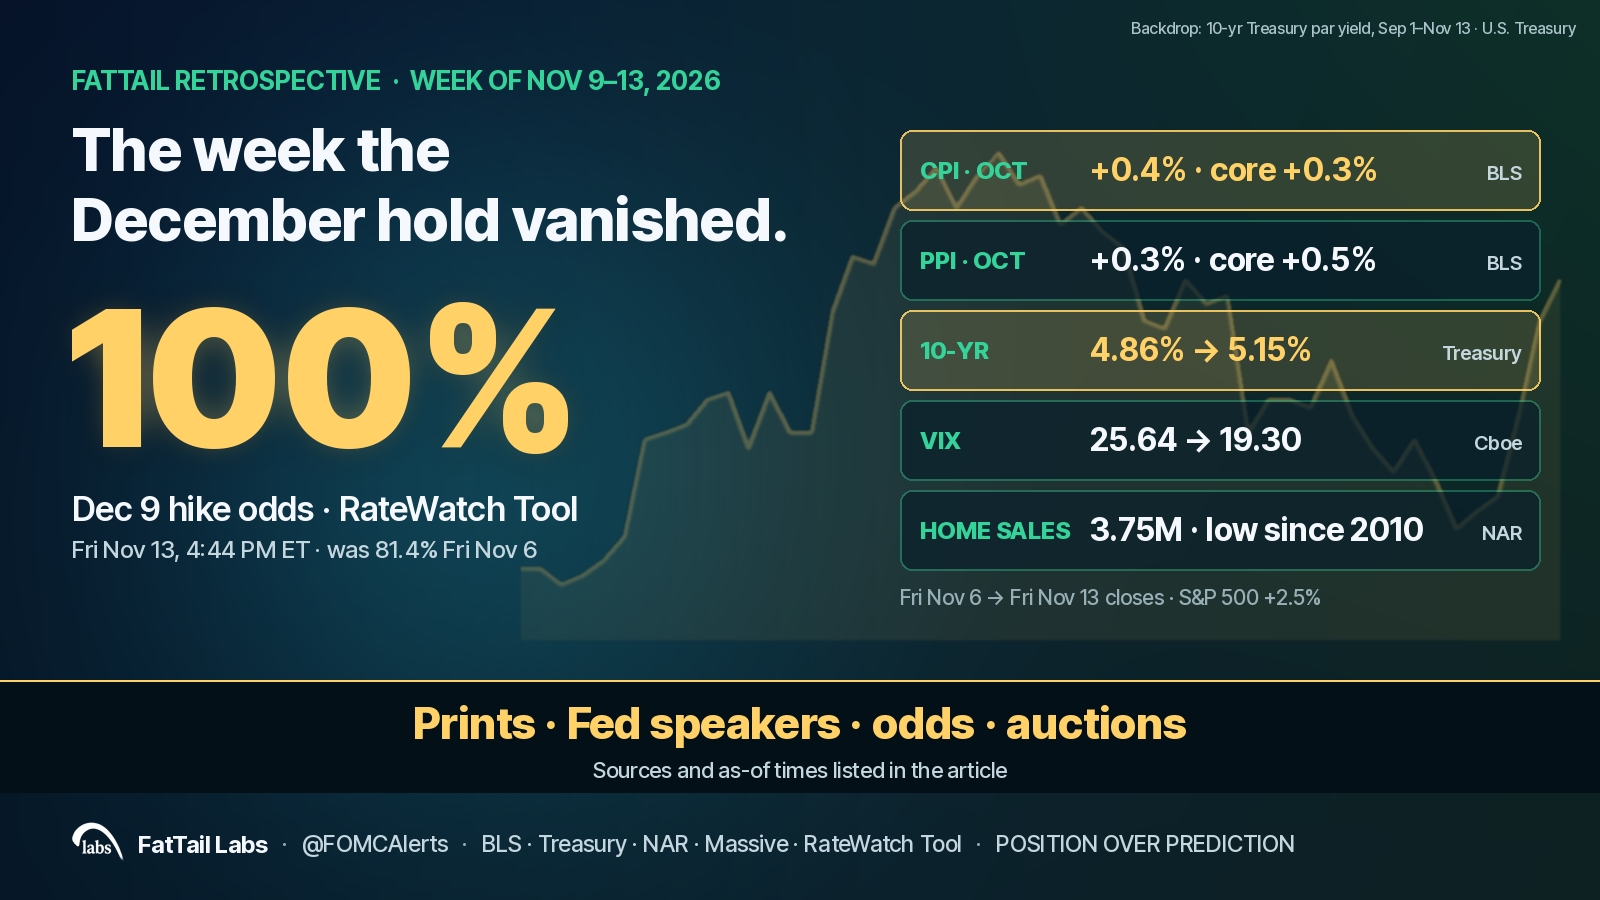
A hot October CPI, a firm PPI core and a parade of hawkish Fed speakers took the December hold off the table. On the RateWatch Tool, Dec 9 hike odds went from 81.4% (Fri Nov 6, 10:44 AM ET) to 100% (Fri Nov 13, 4:44 PM ET). The 10-year Treasury yield rose 29 bp on the week to 5.15%, while stocks rallied and the VIX fell back below 20.
The prints
October CPI (BLS, Tue Nov 10, 8:30 AM). Headline +0.4% m/m, core +0.3%. September was +0.6% headline and +0.3% core. Unrounded, from the BLS seasonally adjusted indexes: headline +0.350% (336.298 to 337.476), core +0.296% (338.896 to 339.900). Consensus differed by source: FactSet (via Morningstar) 0.2% / 0.2%; Dow Jones (via CNBC) 0.3% / 0.2%. Headline beat both, and core came in a tenth above both. BLS published no 12-month rate for all-items or core because October 2025 data were never collected. Our recap: October CPI 2026.
October PPI (BLS, Fri Nov 13, 8:30 AM). Final demand +0.3% m/m after a September revised to +1.4% (from +1.3%); +6.5% y/y, not seasonally adjusted. Official BLS core (less foods, energy and trade services) +0.5%, the same as September. Third-party forecast: XTB 0.4% m/m, so the headline came in a tenth light. Our recap: October PPI 2026.
Existing-home sales (NAR, Thu Nov 12, 10:00 AM). 3.75 million annual rate, down 5.5% from a revised 3.97 million in September and the lowest since August 2010. Third-party previews: FactSet (via AP) 3.8 million; Reuters poll 3.85 million. The median price was $416,700, up 0.4% y/y. Our recap: existing-home sales.
Household debt (New York Fed, Tue Nov 10). $19.1 trillion in Q3, up $334 billion (+1.8%) in the quarter, with 5.0% of debt in some stage of delinquency, up 0.3 point. About half the mortgage increase was re-reporting after a gap the previous quarter. Our recap: household debt Q3 2026.
Consumer expectations (New York Fed SCE, Mon Nov 9). Median inflation expectations were unchanged at 3.9% (1-year), 3.3% (3-year) and 3.0% (5-year). The mean probability that unemployment will be higher a year from now rose 1.4 points to 45.3%, the highest since April 2020.
The Fed
No FOMC decision this week. The target range is 3.75–4.00% after the Oct 28 hold (10–2), and the next decision is Dec 9. The speakers mostly leaned hawkish:
- Waller (Governor, voter) said overnight before the print that a 50 bp December hike should be considered if core is “around 0.3 percent or even higher.” October core printed +0.296%.
- Goolsbee (Chicago, 2026 alternate) called the CPI “borderline disturbing” on PBS on Tuesday night but did not back a 50 bp hike. On Friday he described “old-fashioned demand overheating” from the AI data-center build-out. Goolsbee on CPI.
- Treasury Secretary Bessent said on the same Friday program that the inflation story is an energy supply shock, and that hiking too much into it would be a mistake. Bessent and Goolsbee split.
- Hammack (Cleveland, voter), as quoted by Reuters, prefers “smaller increments, more frequent” hikes. Hammack.
- Barr (Governor, voter) spoke on AI and inequality, noted a record-low 52.8% labor share, and made no rate call. Barr.
- Williams (New York, Vice Chair) spoke on a Thursday-evening panel with no official text. Reuters paraphrased him as saying more hikes are likely. Williams.
- Collins (Boston, non-voter) told Bloomberg TV the direction policy needs to go is “clear,” while declining to pre-commit. Collins.
- Logan (Dallas, voter) said the Treasury market “is functioning very well today,” and that high yields alone are not a sign of dysfunction. Logan.
- Warsh (Chair): a Washington Post piece framed him as an outlier on AI and inflation. We set that framing against his official words. Warsh on AI inflation.
Outside the Fed, a Reuters poll of 101 economists (Nov 6–10, mostly before the print) found all 101 expecting a 25 bp hike in December. That figure is from a third party.
Advertisement · From FatTail Labs

Observer: train with Coach for $17/week
A six-week trial and training program built to install pro trading habits: live daily coaching, courses, a Discord trade room and the full FatTail platform.
Treasury auctions
All three coupon auctions cleared at higher yields as rates rose (TreasuryDirect results):
- 3-year note, $58 billion, Mon Nov 9: high yield 4.627%, bid-to-cover 2.53.
- 10-year note, $42 billion, Tue Nov 10: high yield 5.020%, bid-to-cover 2.46.
- 30-year bond, $25 billion, Thu Nov 12: high yield 5.441%, bid-to-cover 2.36.
The bond market was closed Wed Nov 11 for Veterans Day. Stocks traded.
Volatility and odds
Stocks and vol (Massive, official daily closes). The S&P 500 closed at 7,561.67 on Friday, up 2.5% from 7,376.86 on Fri Nov 6. Its best close was 7,619.38 on Wednesday. The VIX fell from 25.64 to 19.30, with a low close of 17.49 on Wednesday.
Treasury yields (U.S. Treasury daily par yield curve). The 10-year rose from 4.86% (Nov 6) to 5.15% (Nov 13), +29 bp. The 2-year rose from 4.51% to 4.88%, +37 bp, and the 30-year from 5.26% to 5.47%. Treasury published no Nov 11 row because of the holiday.
RateWatch Tool, Dec 9 meeting (our ZQ fed funds futures math):
- Fri Nov 6, 10:44 AM: hike 81.4%, hold 18.6%.
- Mon Nov 9, 4:39 PM: hike 85.2%, hold 14.8%.
- Tue Nov 10, 4:37 PM: hike 100% (+25 bp 89.8%, +50 bp 10.2%), hold 0%.
- Wed Nov 11, 4:40 PM: +25 bp 98.7%, +50 bp 1.3%.
- Thu Nov 12, 4:37 PM: +25 bp 80.1%, +50 bp 19.9%, the week’s highest 50 bp reading.
- Fri Nov 13, 4:44 PM: +25 bp 93.4%, +50 bp 6.6%, hold 0%.
As of the Friday 4:44 PM stamp, January 27 was 70.0% hike and 30.0% hold. These are as-of levels, not a claim about what moved them. Live board: RateWatch Tool.
What it sets up
A December hike is fully priced on our board. The open question is its size: the +50 bp share ran from 1.3% to 19.9% across the week’s closing stamps. October retail sales on Nov 17 and October PCE on Nov 25 are the remaining big inputs before Dec 9. The other things to watch are whether the 10-year holds above 5%, and whether the energy-shock reading (Bessent) or the demand-overheating reading (Goolsbee) gains ground. Sunday’s FatTail Week Ahead has the full calendar.
Related: RateWatch Tool · October CPI 2026 · October PPI 2026
Sources
- Consumer Price Index — Table 1, October 2026 (U.S. Bureau of Labor Statistics, 2026-11-10)
- Producer Price Indexes — October 2026 (USDL-26-1687) (U.S. Bureau of Labor Statistics, 2026-11-13)
- BLS Public Data API v2 (series CUSR0000SA0, CUSR0000SA0L1E, WPSFD4, WPSFD49116) (U.S. Bureau of Labor Statistics, 2026-11-14)
- Daily Treasury Par Yield Curve Rates (U.S. Department of the Treasury, 2026-11-14)
- Treasury auction announcements, data and results (TreasuryDirect, 2026-11-12)
- Existing-Home Sales Decreased 5.5% in October, According to NAR Report (National Association of Realtors, 2026-11-12)
- Household Debt Increased Moderately; Delinquency Transition Rates Remain Flat (Federal Reserve Bank of New York, 2026-11-10)
- October 2026 Survey of Consumer Expectations (Federal Reserve Bank of New York, 2026-11-09)
- RateWatch current odds (public JSON) (FatTail RateWatch, 2026-11-13)
- October CPI Report Shows Inflation at a 0.4% Monthly Rate, Above Forecasts (Morningstar (FactSet consensus); third-party, 2026-11-10)
Educational content, not investment advice.
FATTAIL BRIEFINGS
Get FatTail briefings in your inbox
Pick the lists you want. FOMC Alerts is selected by default.