

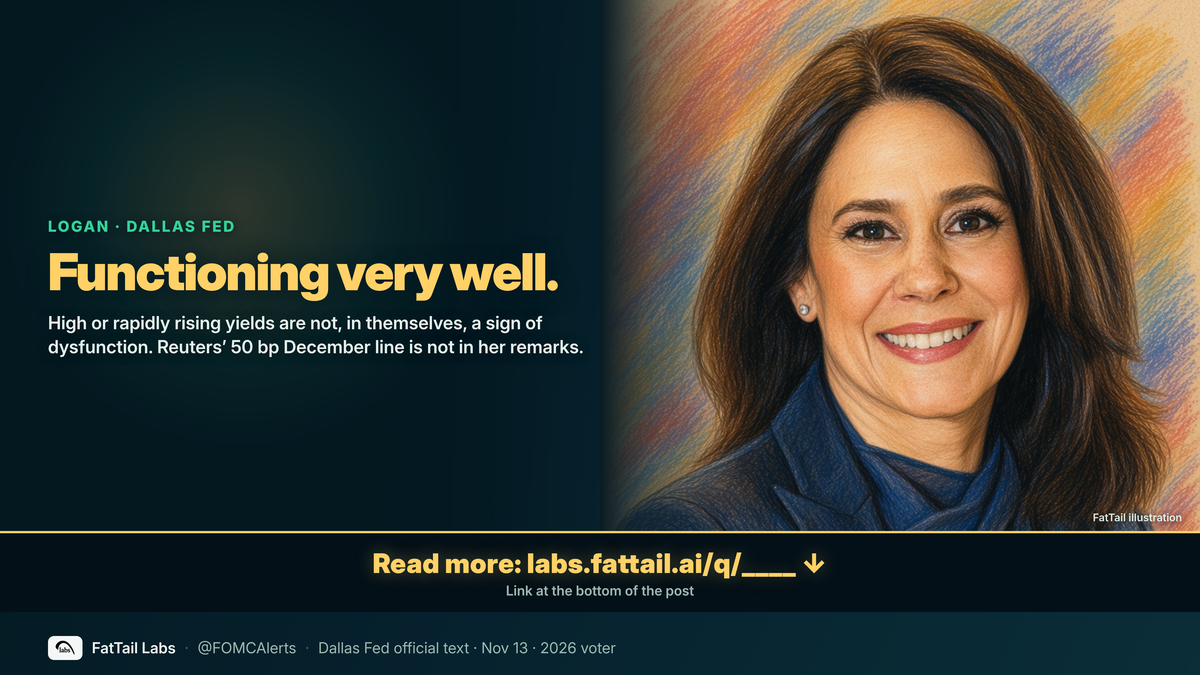
The Logan Treasury market functioning question is what Dallas Fed President Lorie K. Logan, a 2026 FOMC voter, actually addressed in official prepared remarks on Friday morning. The speech, “Operational readiness and bank funding: Considerations for depository institutions and the Federal Reserve,” was delivered as opening remarks at the Dallas Fed conference “Bank Funding in the Age of Instant Finance,” at 8:40 a.m. CT, 9:40 a.m. ET. The official text is up on the Dallas Fed speeches page. Dallas is not a 2027 member or a 2027 alternate; she votes this year.
Two lines are the typographic quotes, in the official typography. First: “The Treasury market ordinarily functions very well and indeed is functioning very well today.” Second: “I don’t see high yields or rapidly rising yields, in themselves, as a sign of dysfunction.”
Logan Treasury market functioning: what the official text says, and what it doesn’t
Later in the same remarks, she judged that the Treasury market is currently functioning very well, and that trading has proceeded smoothly even amid substantial rate volatility. She assesses functioning from measures of liquidity, such as bid-ask spreads, market depth and price impact. The Fed, she said, should intervene only in extreme scenarios of severe dysfunction, and the type of dysfunction that could call for a Fed response is significantly more extreme than merely low liquidity.
She also said that, especially in an economic environment where tighter policy appears necessary, it is prudent for the FOMC to strengthen its tools for supporting market functioning without providing unnecessary economic stimulus. She prefers to use lending tools when possible, because they are straightforward to separate from the policy stance. If purchases are used, the FOMC should be prepared to create that separation if needed, and one way is to hold the purchased securities in a separate account and commit to sell them as soon as possible. A Bloomberg paraphrase that she “should separate assets bought to support market functioning from monetary-policy holdings” is not her sentence; it skips the lending-first point and turns a conditional “one way” into a general holdings rule.
On the policy path, today’s official wording is limited. Inflation is currently trending too high, she said, and as she discussed in a speech earlier this week, it is necessary to make policy more restrictive, not less. That is a citation of her Nov. 10 Houston remarks, not a new December increment, and not a new “two more” call in this text. Reuters’ reminder of “at least two more times, perhaps quickly” is the outlet looking back at Nov. 10, not new wording today.
Reuters, in a Friday wrap, framed a half-point December hike as a market bet after inflation data and comments from other officials, including Governor Christopher Waller. That 50 bp December line is the outlet’s market framing, not her words today. The prepared remarks do not mention December, 50 basis points, or a half-point move. No question-and-answer session is on the agenda after the opening-remarks slot, and no Q&A transcript was found.
Official Treasury par, through Thursday’s close
Official Treasury par, for Nov. 12, shows the 2-year at 4.86%, the 10-year at 5.10%, and the 30-year at 5.43%. From the Nov. 9 official row through Nov. 12, that is a two-session rise of 30 basis points in the 2-year, 22 basis points in the 10-year, and 17 basis points in the 30-year. Those official prints were already on the tape before Friday’s remarks. Do not read the backup as a reaction to this speech, and do not treat a third-party yield ranking as official par.
Advertisement · From FatTail Labs

Observer: train with Coach for $17/week
A six-week trial and training program built to install pro trading habits: live daily coaching, courses, a Discord trade room and the full FatTail platform.
RateWatch, as of 4:44 PM ET
As of 4:44 PM ET on Nov. 13, 2026, RateWatch — our ZQ futures method, never CME FedWatch — prices the Dec. 9 meeting as a 100% hike and a 0% hold, with +25 bp at 93.3% and +50 bp at 6.7%. The same stamp prices the Jan. 27 meeting at 70.0% hike / 30.0% hold, and the March 17 meeting at 67.1% hike / 32.9% hold. The current target range is 3.75–4.00%. That is a single snapshot, not a path, and not a claim that Logan’s remarks, Friday’s PPI print, or any other speaker moved those odds. A 50 bp December outcome remains a minority reading on this stamp, not something she priced or endorsed today.
What it means for 0DTE
Energy: A 2026 voter said the Treasury market is functioning very well today, and that she doesn’t see high or rapidly rising yields, in themselves, as a sign of dysfunction. She wants stronger backstops without unnecessary stimulus, and she did not make a 50 bp December call in this text. Keep Reuters’ December framing labeled as the outlet’s. A 50 bp December hike remains a minority outcome on the 4:44 PM ET RateWatch stamp.
Premium: Thursday’s official close, Nov. 12, was S&P 500 7,592.40, VIX 18.70, and VIX1D 15.99, from Massive’s daily aggregates. Use that settled close as the last official reference until Friday’s official close is in. Do not treat an unofficial Friday print as the close.
Structure: Defined-risk structures only. Official remarks on market functioning are not a reason to size into a 25-versus-50 guess.
Plan: Keep the two official typographic quotes, the Reuters 50 bp December line labeled as market framing, her 2026 voter status, the official Treasury two-session par move through Thursday, and the single RateWatch stamp as of 4:44 PM ET Nov. 13 on the pad. For a walkthrough of how we map a session onto a defined-risk plan, see how to plan 0DTE market scenarios.
For other pieces from this week, see Williams on more hikes likely, Bessent vs Goolsbee on the energy shock, and Collins on more rate hikes.
Sources
- Operational readiness and bank funding: Considerations for depository institutions and the Federal Reserve (Federal Reserve Bank of Dallas, 2026-11-13)
- Bank Funding in the Age of Instant Finance (Federal Reserve Bank of Dallas, 2026-11-13)
- Logan Nov. 10 Houston speech (cited in today's footnote 5) (Federal Reserve Bank of Dallas, 2026-11-10)
- FOMC membership and Reserve Bank rotation (Board of Governors of the Federal Reserve System, 2026-11-13)
- Daily Treasury Par Yield Curve Rates (U.S. Treasury, 2026-11-12)
- RateWatch current odds (public JSON) (FatTail RateWatch, 2026-11-13)
Related reading
- Williams on more hikes likely
- Bessent vs Goolsbee on the energy shock
- Collins on more rate hikes
- October CPI 2026
- October PPI 2026
- Warsh on AI and inflation
- RateWatch
- December Fed meeting 2026
- FOMC voters 2026
- FOMC meeting schedule 2026
- FOMC Alerts
FATTAIL BRIEFINGS
Get FatTail briefings in your inbox
Pick the lists you want. FOMC Alerts is selected by default.