

FOMC Alerts · October 27, 2026
The FOMC implied move this week isn’t one number. SPX and SPY list an options expiry every trading day, and each one has to price whatever lands before its 4:00 PM ET settlement. Daily SPXW options stop trading at 4:00 PM ET on expiration day (Cboe), so an event belongs to the first expiry that settles after it. That turns Fed week into a map: which expiry absorbs which shock, and what each one charges.
Below: the price of each session from Tuesday morning’s option quotes, the hour-by-hour map in ET, and how the session after a Fed decision has behaved since Cboe launched its one-day VIX.
FOMC implied move: what each expiry charges
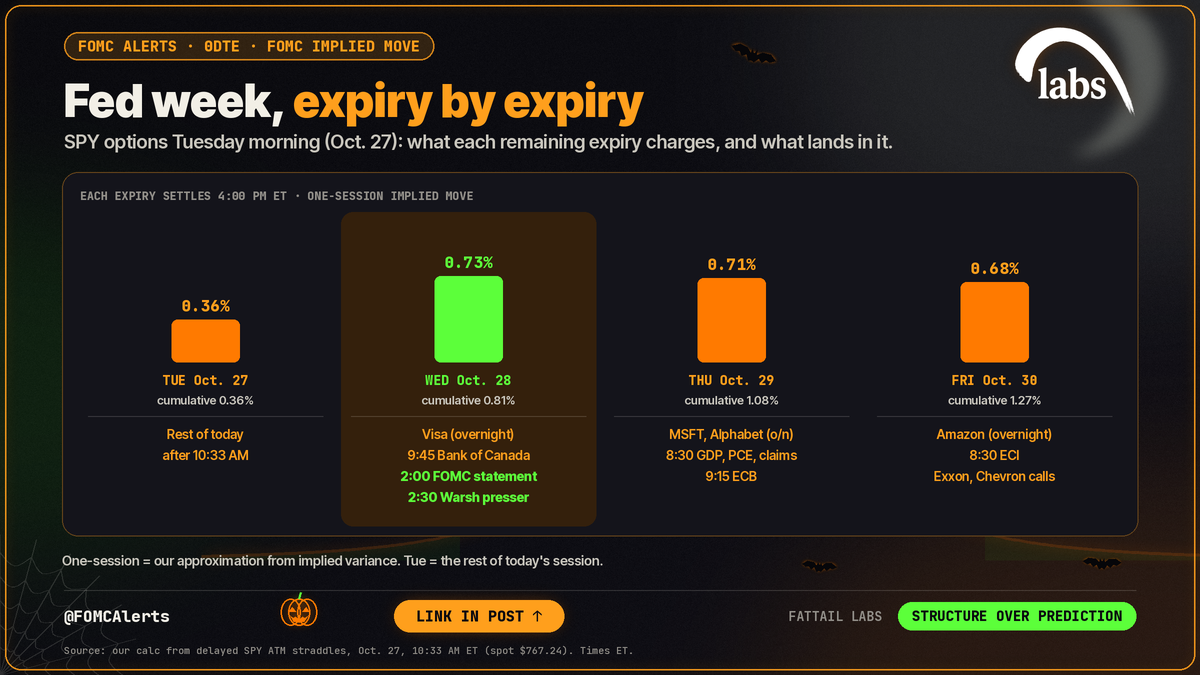
At 10:33 AM ET on Tuesday (Oct. 27), at-the-money SPY straddles priced these moves. The cumulative column is the move priced from that point to each expiry, so Tuesday’s row covers only the rest of today’s session. The column in brackets strips out the earlier days, leaving roughly what that one session is charging.
| Expiry | Cumulative implied move | (One session) |
|---|---|---|
| Tue Oct. 27 (rest of day) | 0.36% | (0.36%) |
| Wed Oct. 28 | 0.81% | (0.73%) |
| Thu Oct. 29 | 1.08% | (0.71%) |
| Fri Oct. 30 | 1.27% | (0.68%) |
Source: our calculation from delayed SPY at-the-money straddle mids, Oct. 27 at 10:33 AM ET, spot $767.24 (Yahoo Finance). Implied move = straddle ÷ spot. One-session figures are our approximation from the change in implied variance between expiries. At Friday’s close (Oct. 23) the same calculation had Wednesday at 0.90%, Thursday at 0.83% and Friday at 0.82%, so some of that premium has bled out since, while VIX1D fell.
Wednesday, the Fed’s expiry, is still the most expensive single session at 0.73%. The surprise is the two days after it. Thursday charges 0.71% and Friday 0.68%, each close to Wednesday. The market isn’t pricing one event. It’s pricing about two days of them.
The hour-by-hour map (all times ET)
From the Bank of Canada at 9:45 AM Wednesday to the open at 9:30 AM Friday is 47.75 hours. Nearly all of the week’s scheduled risk sits in that window.
| Lands in expiry | Event | Time | Hours before that 4:00 PM settlement |
|---|---|---|---|
| Tue Oct. 27 | ADP NER Pulse (weekly payrolls estimate) | 8:15 AM (ADP’s usual time) | 7.75 |
| Tue Oct. 27 | Conference Board consumer confidence | 10:00 AM | 6.0 |
| Wed Oct. 28 | Visa results (Tue after the close) | Overnight | about 24 |
| Wed Oct. 28 | ADP Inc. earnings (not a jobs report) | Before the open | n/a |
| Wed Oct. 28 | Bank of Canada decision | 9:45 AM | 6.25 |
| Wed Oct. 28 | FOMC statement | 2:00 PM | 2.0 |
| Wed Oct. 28 | Chair Warsh’s press conference | 2:30 PM | 1.5 |
| Thu Oct. 29 | Microsoft results (Wed after the close); Alphabet call 4:30 PM Wed | Overnight | about 23.5–24 |
| Thu Oct. 29 | Q3 GDP (advance), September PCE, jobless claims | 8:30 AM | 7.5 |
| Thu Oct. 29 | ECB decision (press conference 9:45 AM) | 9:15 AM | 6.75 |
| Fri Oct. 30 | Amazon results (Thu; call 5:00 PM) | Overnight | about 24 |
| Fri Oct. 30 | Employment Cost Index, Q3 | 8:30 AM | 7.5 |
| Fri Oct. 30 | ExxonMobil call (to 10:30 AM); Chevron call 11:00 AM | 9:30 AM | 6.5 / 5.0 |
Sources: Federal Reserve, BEA, BLS, Bank of Canada, ECB, Conference Board and company investor-relations pages (Microsoft, Alphabet, Amazon, Visa, ADP, ExxonMobil, Chevron). Earnings rows use the release day and the call time the company published.
Two things stand out. Wednesday’s expiry gets the Fed with only two hours left before settlement, so there’s little time for the move to fade or extend before the 4:00 PM mark. Thursday’s expiry opens on top of the Fed reaction, Microsoft and Alphabet overnight, and GDP and PCE at 8:30. For the data detail, see our Q3 GDP preview.
Advertisement · From FatTail Labs

Observer: train with Coach for $17/week
A six-week trial and training program built to install pro trading habits: live daily coaching, courses, a Discord trade room and the full FatTail platform.
The session after the Fed
We compared each day’s realized SPX close-to-close move with the average move implied by Cboe’s one-day VIX (VIX1D) at the prior close (Cboe). Across the 28 FOMC meetings since VIX1D launched in April 2023:
- The session after the Fed beat its implied move 46.4% of the time.
- Fed day itself beat it 35.7% of the time.
- All other days beat it about 36% of the time (824 days).
Adding Cboe’s backfilled history from June 2022 (35 meetings) gives a similar split: 48.6% for the day after, 37.1% for Fed day. In 2026 the day after beat its implied move in four of six meetings, Fed day in three.
That’s our calculation, and it’s a small sample. “Beat” means the close-to-close move was bigger than the average implied move, not that any trade made money. This week, the session after the Fed is Thursday’s expiry, the one already carrying Big Tech earnings and the 8:30 data.
For context, Cboe’s volatility indexes closed Monday, Oct. 26, at 10.49 (VIX1D), 17.92 (VIX9D), 18.39 (VIX) and 19.94 (VIX3M). We explain how those fit together in VIX term structure explained. Fed funds futures still price a hold on Wednesday, about 90% by our calculation from fed funds futures using CME’s method (CBOT via Yahoo Finance, delayed; method in our guide to Fed rate odds). The full calendar and odds are in our Fed meeting this week preview.
What it means for 0DTE
- Energy: all of this week’s big risk is scheduled. Know which expiry you’re in before you trade it: Wednesday’s carries the Fed for its last two hours, Thursday’s carries the reaction plus earnings and data.
- Premium: the options already charge for the cluster, about 0.7% a session Wednesday through Friday on Tuesday morning’s quotes. That’s the SPX expected move, and a “big move” has to beat it to matter. After-close earnings can leave next-day premium rich, then crush it; see IV crush after earnings.
- Structure: with two hours from statement to settlement, Wednesday leaves little room to repair a position. Keep risk defined and size for a gap on Thursday’s open.
- Plan: write scenarios for Wednesday’s last two hours and Thursday’s open separately; don’t predict the direction. Our scenario-planning guide walks through it.
When is the next FOMC meeting?
This week’s decision comes Wednesday, Oct. 28, at 2:00 PM ET. The next FOMC meeting after that is Dec. 8-9, with the decision on Wednesday, Dec. 9. Every remaining date is in our FOMC meeting schedule 2026, and all of our Fed-week coverage is on the FOMC Alerts hub.
Related reading: VIX term structure explained · How to plan market scenarios for 0DTE SPX · IV crush after earnings · Fed meeting this week · More FOMC Alerts
Sources
- SPX options product specifications (Cboe, 2026-10-24)
- VIX1D, VIX9D, VIX, VIX3M and SPX daily history (Cboe, 2026-10-26)
- SPY options chains, expiries Oct 27-30 (Yahoo Finance (delayed), 2026-10-27)
- 30 Day Fed Funds futures (ZQ) (CBOT via Yahoo Finance (delayed), 2026-10-23)
- October 2026 calendar (Federal Reserve, 2026-10-24)
- Release schedule (BEA, 2026-10-24)
- Employment Cost Index release schedule (BLS, 2026-10-24)
- Upcoming events (Bank of Canada, 2026-10-24)
- Governing Council meeting calendar (ECB, 2026-10-24)
- Consumer Confidence (The Conference Board, 2026-10-24)
- Microsoft announces quarterly earnings release date (Microsoft, 2026-10-07)
- Alphabet investor events (Alphabet, 2026-10-24)
- Amazon Q3 2026 earnings (Amazon, 2026-10-24)
- Visa to announce fiscal Q4 results on Oct. 27 (Visa, 2026-10-24)
- ADP to announce fiscal Q1 2027 results on Oct. 28 (ADP, 2026-10-24)
- 3Q 2026 earnings call (ExxonMobil, 2026-10-24)
- 3Q 2026 Chevron earnings conference call (Chevron, 2026-10-24)
Trade it with structure
Observer is a six-week trial and training program: train with Coach for $17/week. You get everything a full coaching member gets, every week, and the six weeks are designed to install pro trading habits: courses on strategy, process and risk management, live daily coaching, a Discord trade room with hundreds of experienced traders, and the platform (heatmap, GEX tools, risk graph, position analyzer and journal). Start Observer.
Educational content, not investment advice. Options involve risk and are not suitable for all investors.